
By Liesl Peyper.
African Bank Group has reported a marginal growth in its net profit after tax for the year ended 30 September 2024, the group announced on Sens on Tuesday.
The group says the rise from R521 million in FY2023 to R523 million in FY2024 was “satisfactory,” given that a deliberate strategy was employed to curb growth in unsecured personal loans over the period.
Interest income over the period was down 4% to R7 billion (2023: R7.3 billion), while there was also a slower-than-expected conversion of business and commercially approved loans, it notes.
A shift to lower-yielding credit card and overdraft products and the integration of lower-yielding secured lending in its business and commercial segment resulted in a net interest margin decline to 9.7% (2023: 10.9%).
Non-interest and net insurance income were up 14% in the period under review.
Credit loss ratio improvement
A highlight of the results was the 20% improvement in credit impairment charges to R2.6 billion (2023: R3.3 billion), resulting in a corresponding decline in the credit loss ratio to 6.3% (2023: 8%).
The group attributes this to the book diversification to secured lending, refining of credit granting criteria and improved collection and rehabilitation processes.
Another positive was the successful containment of operating expenses, which dropped 1% over the period, with a slight increase in the cost-to-income ratio of 58.7% (2023: 57.2%).
Growth in advances
Net advances were up 8% over the period, with the business and commercial segment comprising 38% of the advances to customers.
Business and retail deposits comprised 92% (2023: 87%) of total funding, which increased to R35.5 billion from R34.6 billion in the prior period.
The group says it has a robust capital adequacy position with a total capital adequacy ratio of 31.4%.
During the period under review, the customer base expanded by 36% to 5.4 million across all group platforms. Personal banking customers were up 17%, while the Alliance banking partnership segment, including that with Shoprite Checkers, Lesaka, and MTN’s Momo – has led to another 3.2 million customers.
Group CFO Anbann Chetti says that although the group has tightened its credit-granting criteria, there is still strong demand for credit, with an average of around 100 000 applications per month. The majority of these applications are submitted through the group’s 436 branches nationwide.
Business and commercial segment
The full integration and divisionalisation of Grindrod Bank into the Business & Commercial division of African Bank was completed in this financial year.
The acquisition of Sasfin’s commercial property finance advances book and operations was approved in August 2024, while the completion of the acquisition of the capital equipment finance book took place after the year-end on 1 November 2024.
“This will further add impetus to the Group’s Business & Commercial growth strategy,” it notes.
Outlook
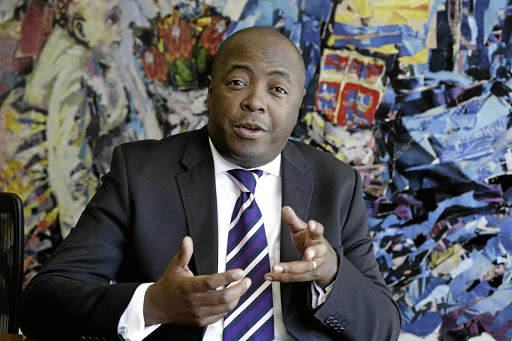
During the group’s results presentation, Kennedy Bungane, the group CEO, said that African Bank will expand its home loan offering to customers in the new year. The facility is currently only available to African Bank staff members.
The group also plans to onboard more partners in its Alliance Banking partnerships, including fintech and non-banking firms. The current insurance offering will be broadened beyond funeral insurance and credit lending.
According to Bungane, the group is now entering its “second phase of pre-initial public offering (IPO)” preparations after securing the Government Employees Pension Fund (GEPF) as its anchor shareholder.
The listing is planned for 2027, he notes.
“In partnership with our anchor shareholder, we are now addressing management alignment issues and BEE ownership of the bank. It’s important to take the bank’s ownership back to the black entrepreneurs who founded it in 1964.”